


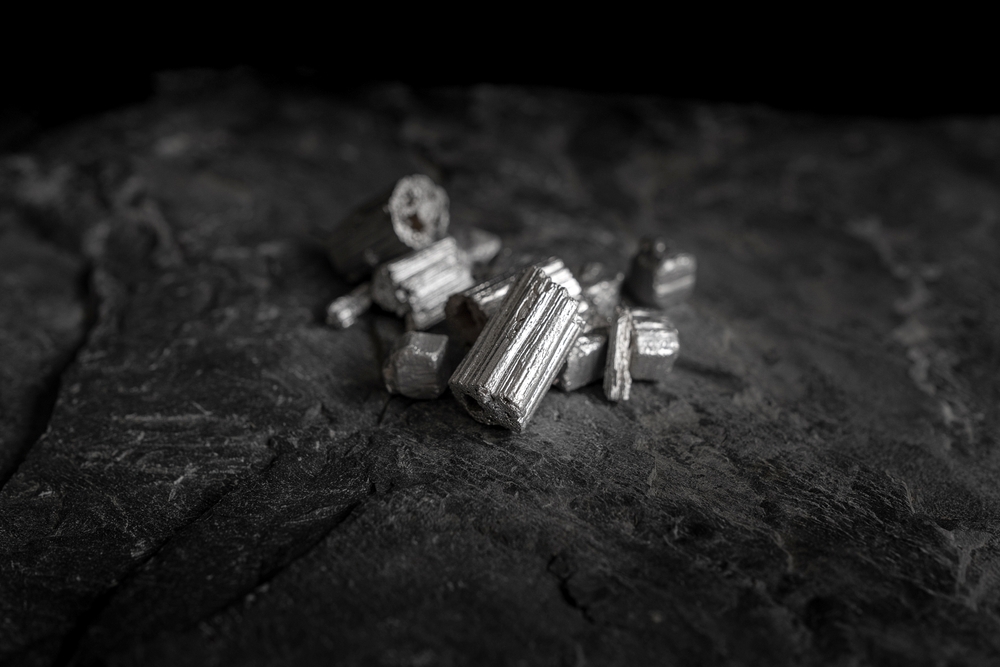
The platinum industry is confronting a familiar problem from a new angle.
As electric vehicles erode the metal’s traditional stronghold in automotive catalytic converters, a fledgling hydrogen economy is emerging as a potential replacement demand source.
However, according to mining analysts, the real constraint on that future may not be technology or investment, it may be the ground itself.
The tension was explored in a recent episode of GlobalData’s Energy Technology podcast, hosted by mining editor Alejandro Gonzalez with guests Edward Sterck of the World Platinum Investment Council, hydrogen researcher Una O’Hara, and GlobalData mining analyst Sai Dheeraj Karanam.
Automotive platinum demand is forecast to decline 4 per cent in 2026 as battery electric vehicles take a growing share of the global fleet, according to the World Platinum Investment Council.
Hydrogen applications, by contrast, are expected to grow 8 per cent over the same period, though from a much smaller starting point.
Sterck noted the council’s base case projects battery electric vehicles will reach 28 per cent of global market penetration by 2030, translating into roughly 1.5 per cent annual declines in combined platinum and palladium automotive demand over the next five years.
Platinum’s role in hydrogen technology stems from its use in proton-exchange membrane fuel cells and electrolysers, where the metal catalyses the reactions that split water into hydrogen and later convert hydrogen back into electricity.
Researchers have looked for cheaper substitutes, but none have matched platinum’s ability to withstand the repeated stress of hydrogen cycling without degrading.
Yet the mining side of the equation is where the story tightens considerably.
Primary platinum production remains heavily concentrated in South Africa, and bringing new mines online is a slow process, often taking a decade from discovery to first output.
That timeline creates a structural mismatch: hydrogen demand could accelerate far faster than new supply can be developed.
“If hydrogen demand rises sharply, it is more likely to add pressure to an already tight market than to trigger a rapid increase in mine supply,” Karanam said.
Current data reinforces that concern.
Mine supply is projected to flatten through 2026, with most near-term growth in overall platinum availability expected to come from recycling rather than new extraction.
That leaves the market with limited flexibility to absorb a demand shock, whether from hydrogen infrastructure buildout or other emerging uses.
Complicating the picture further is a thrifting trend already underway among equipment manufacturers, who are reducing the amount of platinum used per fuel cell or electrolyser to control costs, similar to reductions seen historically in catalytic converters.
Loadings in heavy duty fuel cell trucks are expected to fall from around 50 grams per vehicle today toward 30 grams within a decade.
Whether total platinum demand from hydrogen still rises depends on whether the pace of new deployments outstrips those efficiency gains.
Mining companies are not standing by passively.
Producers have begun funding downstream hydrogen market development, working alongside public subsidy programs, particularly in Europe, to help hydrogen infrastructure reach commercial scale.
The strategy reflects an awareness that expanding demand alone will not solve the supply problem, and that a healthy hydrogen market ultimately depends on adequate metal being available to serve it.
Global committed investment in clean hydrogen has reached approximately $130 billion, according to Hydrogen Council data, though supply readiness continues to outpace firm demand commitments, regulatory clarity, and distribution infrastructure.
For now, the mining industry’s message is one of cautious realism.
Hydrogen may represent a genuine long term growth avenue for platinum, but the sector’s ability to capitalise on it hinges less on catalyst chemistry and more on whether enough new metal can be pulled from the ground in time.
“Hydrogen is a longer term growth opportunity for platinum, but tight mine supply is the more immediate issue,” Karanam said.