


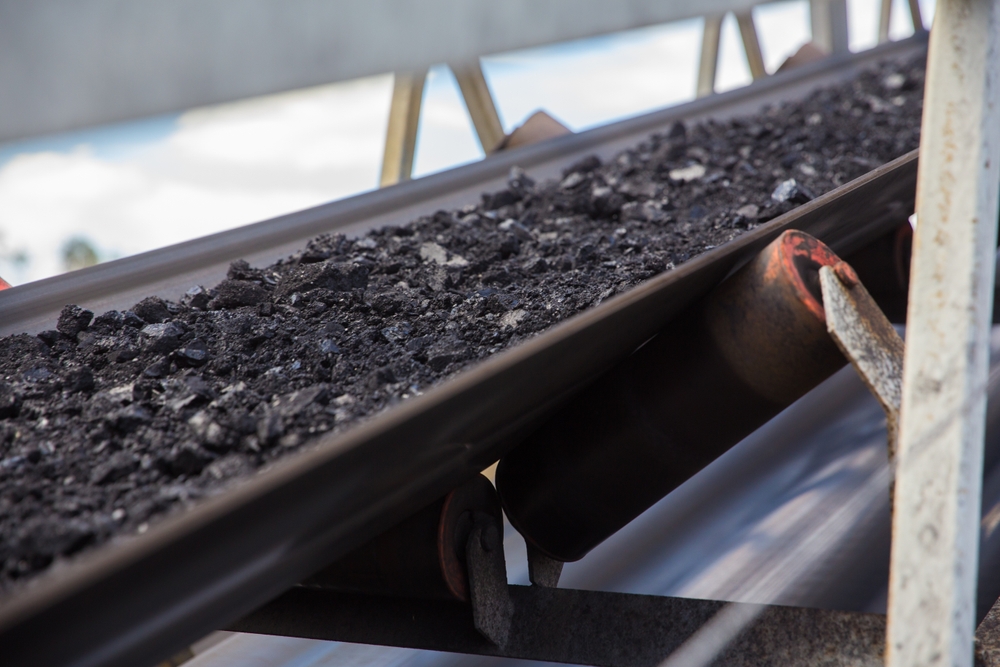
Global coal demand is poised to remain resilient well beyond current expectations, with coal-fired power generation potentially retaining dominance through 2030, according to a new report from Wood Mackenzie.
The Horizons report, titled Staying power: How new energy realities risk extending coal’s sunset, highlights how emerging energy and geopolitical factors could extend coal’s role as a critical power source into the next decade and beyond.
Wood Mackenzie points to multiple influences driving this extended demand, including the rapid electrification of the global economy, heightened energy security concerns resulting from geopolitical tensions and cost shocks, and the presence of a young and evolving coal fleet in Asia.
Together, these dynamics could delay the anticipated phase-out of coal, the world’s most carbon-intensive fuel, during a crucial decade for climate action.
“Extending coal’s prominence through 2030 would fundamentally alter the global energy transition timeline,” said Anthony Knutson, global head of thermal coal markets at Wood Mackenzie.
“We’re talking about delaying the phase-out of the world’s most carbon-intensive fuel source during a critical decade for climate action.
“While the long-term trajectory towards renewables remains intact, the path is proving far more complex than many anticipated as countries grapple with energy security and affordability concerns.”

Under Wood Mackenzie’s base-case Energy Transition Outlook, coal-fired power generation is expected to decline by nearly 70 per cent between 2025 and 2050, driven by falling renewable energy costs, advances in battery storage, a resurgence in nuclear energy, and expanded natural gas capacity.
However, the new Horizons report introduces a ‘high coal demand’ scenario, where coal generation could remain on average 32 per cent higher than the base case through 2050.
This scenario assumes global coal fleets operate at optimised capacity to meet steep energy demand growth, resulting in significantly less deployment of renewables and gas.
The consequences of this high-demand case could include 2,100 gigawatts less installation of wind, solar, energy storage, and natural gas capacity worldwide between 2025 and 2050.
Without investments in carbon capture and storage, unabated coal emissions would rise by two billion tonnes compared to the base case scenario.
Investment challenges also loom as a crucial factor.
“Private equity and sovereign wealth funds will be needed to fund greenfield and brownfield mine expansions,” Knutson said.
“We expect most Western financial institutions to continue limiting thermal coal investments, with the strongest impact on supply growth from 2025-2030 and longer-term market implications if supply replacement momentum is not maintained.”
Insufficient investment could lead to supply constraints and higher coal prices, potentially eroding coal’s cost advantage and curbing demand over time.
The report also underscores the potential role of carbon capture, utilisation, and storage (CCUS) technology to extend coal’s viability in a decarbonising world.
“CCUS could theoretically transform coal’s environmental profile by capturing carbon dioxide emissions before they enter the atmosphere, but the economics remain challenging without substantial policy support and capital investment,” said David Brown, director of the energy transition practice at Wood Mackenzie.
He added: “Higher coal utilisation rates would improve the investment case, but we’re still years away from cost-competitive deployment at scale, particularly in Asia, where carbon storage costs are likely to limit widespread adoption.”
As nations recalibrate energy strategies prioritising sovereignty, affordability, and reliability, the report indicates a significant transformation in global energy planning.
While the scenario of prolonged coal demand highlights risks of delayed climate progress, experts emphasise that policy innovation and investments can help avert the worst outcomes.
“Despite potential higher coal demand, we have the tools to phase it out,” Brown concluded.
“Without urgent actions, the world faces a growing risk of drifting towards a 3 degrees Celsius pathway.
“Our high coal demand case is not a forecast, but it’s a warning of what inaction could bring, and a reminder of what can still be prevented.”


